






Summary of this article
AA-enabled personal loans average Rs 2.67 lakh, exceeding non-AA loans.
First-time borrowers account for a larger share of AA-enabled lending.
AA-enabled personal loans show slightly lower delinquency than non-AA loans.
Personal loans issued through the Account Aggregator (AA) framework have had a higher average loan size than those issued without it, according to a report by CRIF and Sahamati. The report, titled Consent To Credit-The Digital Way: The Account Aggregator (AA) Impact, has found that lenders using the framework have accounted for a larger share of first-time borrowers.
As of June 2026, the average personal loan size for AA-enabled loans stood at Rs 2,67,500, compared to Rs 1,81,100 for loans issued without the framework. However, the difference does not establish that using an Account Aggregator has directly led to larger loans.
What Is The Account Aggregator Framework
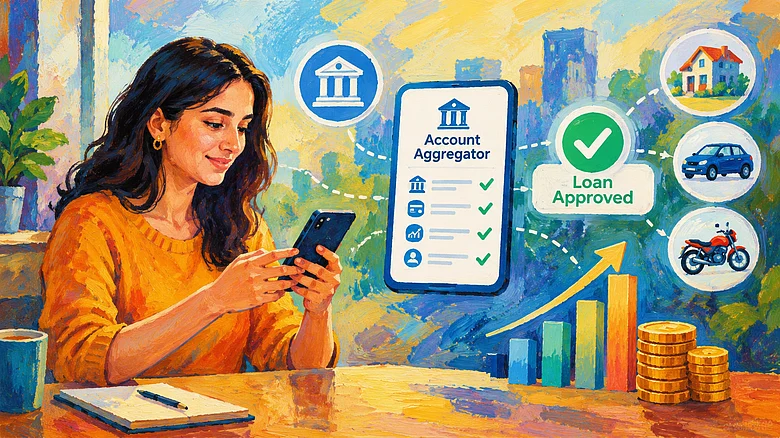
AAs allow borrowers to share their financial information with lenders digitally, after giving their consent. This enables lenders to examine bank transactions and cash flows without asking customers to collect and submit multiple financial documents manually.
This information can help lenders assess whether a borrower can repay a loan. It can also provide additional insights for those with limited credit histories, allowing lenders to assess them solely through conventional methods.
AA-Enabled Lenders Reach More First-Time Borrowers
The report has found a significant difference in the share of new-to-credit (NTC) borrowers across the two groups.
In the 12 months ending June 2026, first-time borrowers accounted for 9 per cent of personal loan originations by AA-enabled lenders. The share stood at 3.8 per cent for lenders that did not use the framework.
A similar difference has emerged in business lending. For loans between Rs 10 lakh and Rs 25 lakh, new-to-credit borrowers accounted for 28.5 per cent of originations among AA-enabled lenders, compared with 8.6 per cent among non-AA lenders.
These findings suggest that access to bank account data may help lenders assess applicants who have limited or no previous borrowing records. However, the report does not establish that the framework alone has driven this difference.
Higher Average Loan Sizes Across Other Categories
The report has also found higher average ticket sizes for AA-enabled loans in other categories. For auto loans, the average size has reached Rs 8,14,270 for AA-enabled loans, compared with Rs 6,84,800 for loans issued without the framework. In the two-wheeler loan segment, the average for AA-enabled loans was Rs 1,15,400, and Rs 1,03,890 for non-AA loans.
Through this difference, we can understand that loans processed using the framework had higher average ticket sizes across these categories. However, loan amounts can also depend on borrowers' income, repayment capacity, credit profiles and lenders' assessment practices.
Are AA-Enabled Loans Being Repaid Better
The report has recorded a slightly lower delinquency rate for AA-enabled personal loans. The share of loans overdue by 90 days or more, measured by the PAR 90+ metric, has stood at 2 per cent for AA-enabled loans, compared with 2.2 per cent for non-AA loans.
Even though the findings suggest a marginal variation in the repayment discipline between these two groups, it does not establish the fact that sharing bank information is directly proportional to improved repayment behaviour.





