


Summary of this article
Mumbai consumer commission ordered Care Health Insurance to pay Rs 35,000
Insurer denied cashless approval for brain aneurysm surgery citing non-disclosure
Commission found no established link between earlier ailments and brain aneurysm
Estimated Rs 20 lakh surgery claim was premature as treatment had not occurred
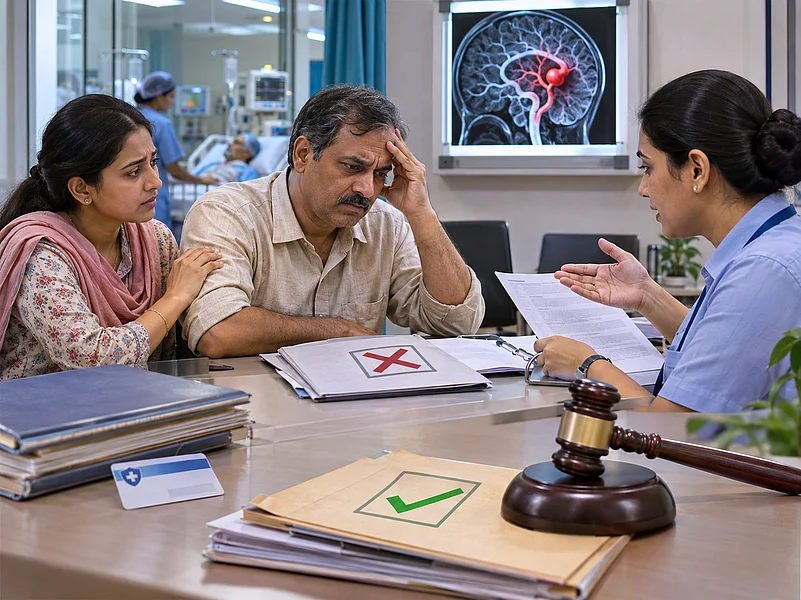
A man who had maintained health insurance since 1996 was denied cashless pre-authorisation for treatment of a brain aneurysm after porting his policy to Care Health Insurance. The Mumbai Central District Consumer Disputes Redressal Commission has now directed the insurer to pay him Rs 30,000 as compensation and Rs 5,000 towards litigation costs.
The order does not require the insurer to pay the estimated Rs 20 lakh cost of surgery. The commission said that the claim was premature because the man had not undergone the operation.
Aneurysm Found After Policy Was Ported
The complainant, Mehul Gandhi, had a mediclaim policy with United India Insurance since March 1996. It covered him, his wife, and daughter. In September 2022, he ported the policy to Care Health Insurance. The new policy provided a sum insured of Rs 25 lakh and cost Rs 56,036 in premium, according to a recent report by The Times of India.

2 November 2026
Get the latest issue of Outlook Money

According to the complaint, Gandhi told the insurer during a telephone conversation that he and his wife were taking medication for hypertension. He also disclosed his daughter’s earlier treatment for a throat infection.
In December 2022, Gandhi felt lightheaded while in Igatpuri and underwent medical tests, including an MRI. He was diagnosed with an intracranial aneurysm, for which surgery was estimated to cost around Rs 20 lakh. He sought cashless pre-authorisation for treatment.
The insurer asked for his medical records relating to Bell’s palsy in 2009 and a fainting episode in 2021. Gandhi’s doctor said the Bell’s palsy had been treated at home, while the fainting episode occurred during routine blood collection. Care Health denied the cashless request on January 6, 2023, citing non-disclosure of a pre-existing ailment.
The insurer argued before the commission that Gandhi had withheld medical information and breached the duty of good faith. It also said he had sought cashless pre-authorisation but had not undergone treatment or submitted a reimbursement claim.
Commission Finds No Link Between Conditions
The commission noted that Gandhi’s insurance cover had continued from 1996 until the policy was ported in 2022. It held that the Bell’s palsy and fainting episodes had occurred while his earlier policy was active. They therefore could not be treated as undisclosed pre-existing diseases when he moved to Care Health.
The panel also found that the insurer had not established a connection between those past conditions and the brain aneurysm. Medical records noting a past illness did not, by themselves, prove that the policyholder had suppressed it, the commission observed.
It held that denying cashless hospitalisation on this basis amounted to an unfair trade practice. Care Health was directed to pay Rs 30,000 for the mental agony and harassment caused to Gandhi, along with Rs 5,000 in litigation costs, within 60 days of receiving the order.
The commission did not award the estimated surgery cost. Since Gandhi had not undergone the operation, there was no actual treatment expense to reimburse. Cashless pre-authorisation is a facility, the commission noted, and a claim for the cost of future treatment could not be decided before that treatment took place.
For policyholders considering portability, the case highlights the importance of checking that continuity benefits are recorded in the new policy and retaining documents from the previous insurer. The commission’s ruling turned on the uninterrupted coverage and the absence of evidence linking the earlier conditions to the ailment for which treatment was sought. It does not mean every cashless request after portability must be approved; policy terms and the facts of each claim still matter.
FAQs
Why did Care Health Insurance deny the cashless request?
The insurer cited non-disclosure of the policyholder’s past Bell’s palsy, treating it as a pre-existing condition.
What did the consumer commission order Care Health to pay?
It directed the insurer to pay Rs 30,000 as compensation and Rs 5,000 towards litigation costs.
Did the commission order reimbursement of the estimated Rs 20 lakh surgery cost?
No. The surgery had not taken place, so the commission considered the reimbursement claim premature.