





Summary of this article
Whenever you get a raise, you should be investing that money to grow your nest egg further.
Try to increase your monthly SIP each year even if it’s a small amount. You will notice the difference when it’s longer.
With higher salaries come higher expenditure. You need to find that balance and spend on things you want to while increasing your investment amount.
Usually, an increase in your salary is considered good for your finances. However just because you have more money doesn't mean you're wealthy. If most of the additional money is quickly absorbed by a bigger rent, a more expensive car, frequent dining out or other lifestyle upgrades, the financial benefit of the raise can disappear surprisingly quickly.
This is where lifestyle inflation becomes a problem. There is nothing wrong with spending more as income rises. The issue is when expenses rise as quickly as, or faster than, investments.
Ideally, every salary increase should have two beneficiaries: your present lifestyle and your future self. The key is to make sure the latter gets a meaningful share of the increase.
Let The SIP Get The First Share
A simple rule investors can consider is to direct at least 50 per cent of every increase in take-home pay towards investments.
For example, if a salary hike results in an additional Rs 10,000 a month, Rs 5,000 could immediately be added to the monthly systematic investment plan (SIP). The remaining Rs 5,000 can be used for lifestyle upgrades or discretionary spending.
This approach allows a person to enjoy the benefits of a higher salary without allowing every increment to become a permanent increase in monthly expenses.
“The first question after a salary hike should be how much more can be invested, not how much more can be spent,” says Krishanu Choudhary, Director & Unit Head, Anand Rathi Wealth Limited.
One practical way of following this discipline is to increase investments as soon as the salary changes rather than waiting until the end of the month to see what is left. If the additional money is automatically invested, there is less temptation to spend it.
Don't Let Lifestyle Upgrades Eat Into Financial Goals
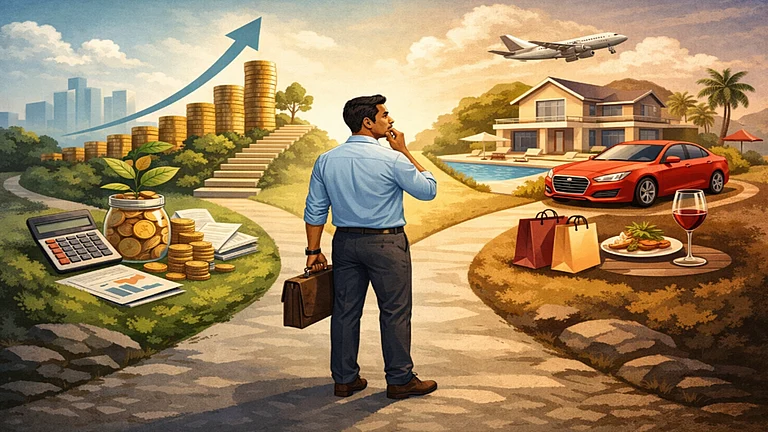
A salary increase can make previously unaffordable purchases look manageable. A more expensive car, a larger home or more frequent holidays may all be reasonable choices, but they can also create recurring expenses that continue long after the initial salary hike.
“Financial goals should, therefore, be kept separate from lifestyle spending,” says Choudhary.
If you expect to buy a car in three years or a house in 10 years, the money required for those goals should be planned for independently. Waiting until the purchase is close can put pressure on savings and investments.
Similarly, before increasing discretionary spending, investors should check whether their emergency fund is adequate, insurance cover is sufficient and expensive debt is under control. A salary hike is more valuable when it improves financial security rather than simply increasing consumption.
Small Increases Can Make A Big Difference
The impact of increasing investments becomes more visible over long periods because the additional money gets more time to compound.
“For example, a Rs 10,000 monthly SIP invested for 20 years at an assumed annual return of 13 per cent can build a corpus of roughly Rs 1 crore. If the SIP is increased by 10 per cent every year, the potential corpus can move towards Rs 2 crore. A 15 per cent annual step-up can take it closer to Rs 3 crore, assuming the same return over the entire period,” says Choudhary.
These are, however, illustrations, not guaranteed returns. Actual investment returns will vary depending on the asset class and market conditions.
The larger point is that a relatively small increase in the amount invested each year can have a significant effect over two decades.
The Early-Career Advantage
The temptation to postpone higher investments is particularly strong early in a career. With fewer financial responsibilities, it can feel reasonable to spend more today and promise to invest more once the salary becomes significantly higher.
The problem is that responsibilities usually increase with income and age. A home loan, children's education, family commitments and other expenses can make it harder to redirect a large portion of income towards investments later.
Starting early does not necessarily mean living a restricted lifestyle. It means deciding in advance how much of every income increase should go towards future goals.
“A useful way to think about a salary hike is to split it between lifestyle inflation and wealth creation. If the entire increase goes towards consumption, the person may earn more without becoming financially stronger. If a meaningful portion goes towards investments, the salary hike can improve both the quality of life today and financial freedom later,” advises Choudhary.


The objective is not to avoid enjoying a higher income. It is to ensure that lifestyle expenses do not rise faster than investments.
That is when a salary hike starts doing more than making the monthly bank balance look better - it starts building wealth.





