

Summary of this article
GIC reportedly considering mandatory 10 per cent health insurance co-payment
Policyholder contribution could be capped at Rs 5 lakh per claim
Lower premiums may mean higher out-of-pocket hospitalisation expenses
Room-rent deductions and consumables could increase costs beyond co-payment
The General Insurance Council (GIC) is reportedly considering a proposal to introduce a mandatory 10 per cent co-payment in retail health insurance policies, with the policyholder’s contribution potentially capped at Rs 5 lakh per claim. When contacted, GIC declined to comment. The reported proposal remains under discussion.
The proposal aims to address rising healthcare costs and potential distortions in hospital billing. However, if implemented, it could increase the out-of-pocket burden for health insurance policyholders, particularly those facing large hospitalisation expenses.
The proposed model would mean lower premiums upfront, but policyholders would have to bear a part of the hospital bill when they make a claim.
What Does A 10 Per Cent Co-Pay Mean?
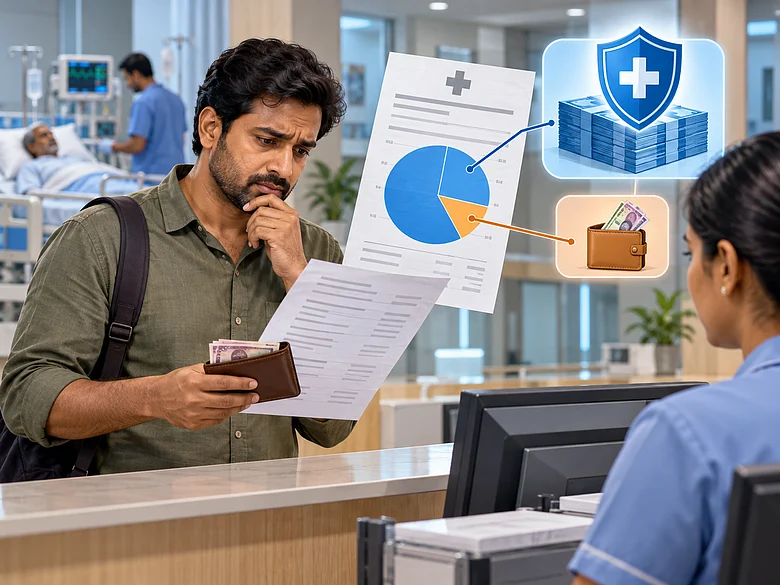
“A 10 per cent co-pay means the policyholder bears 10 per cent of the admissible claim amount, while the insurer pays the remaining 90 per cent,” says Ramkumar Subramanian, partner, Grant Thornton Bharat.
For example, if a hospitalisation claim has an admissible amount of Rs 5 lakh, the policyholder would contribute Rs 50,000, and the insurer would settle Rs 4.5 lakh, subject to the terms and limits of the policy.
That liability can become significant for expensive treatments. A 10 per cent co-pay on a Rs 25 lakh admissible hospital bill, for instance, would mean a Rs 2.5 lakh contribution from the policyholder.
The percentage stays the same, but the rupee amount grows with the size of the bill. A larger sum insured may provide more cover, but the policyholder would still need money to meet the co-payment.
Lower Premiums, Greater Liability At Claim Time
“Co-pay is essentially a cost-sharing feature in health insurance. It can help reduce premiums, but it also increases the policyholder's out-of-pocket expense at the time of a claim,” says Subramanian.
For a healthy, younger policyholder who rarely claims, that can be a fair deal. However, the calculation changes for someone who needs prolonged treatment or is likely to be hospitalised frequently.
“However, it should be realized that lower premiums mean greater liability at the time of making a claim. Although it may be irrelevant in the case of low medical expenditures, it might become substantial in case of a prolonged treatment process,” says Arun Ramamurthy, co-founder, Staywell.Health.
Whether a 10 per cent co-pay is suitable depends on the individual's age, health condition, affordability, and preference for lower premiums versus higher claim-time coverage.
Consumers should look beyond the premium and understand the financial contribution they may have to make during hospitalisation. The premium saving needs to be considered alongside the amount they could afford to pay if a claim arises.
Why Your Payment Could Exceed 10 Per Cent
“The co-pay applies only to the admissible portion of the claim, so non-payable items, room-rent differences and any deductions come on top of it,” says Sarita Joshi, head of life & health insurance, Probus.
The distinction between the hospital’s total bill and the admissible claim amount matters. Co-payment is calculated on the amount eligible under the policy. Expenses excluded from that amount would still need to be paid separately.
“However, in practice this may go even higher if a consumable cover is not taken. We are seeing that 10-25 per cent is deducted in claim under this head, which is then paid as out-of-pocket expenses,” says Shilpa Arora, co-founder & COO, Insurance Samadhan.
The eventual payment therefore depends on the policy’s coverage, exclusions and deductions, alongside the co-pay percentage. Policyholders should not assume that their total expense will stop at 10 per cent of the hospital bill.
“For bigger claims like a cancer treatment which may cost Rs 30-40 lakh, the policyholder will have to pay somewhere close to four to five lakh out of pocket. This can put a significant burden on the policyholder for high-value claims,” says Arora.
What Should Policyholders Prepare For?
Repeated hospitalisation can also increase the burden because the policyholder would pay their share each time. With medical costs climbing, the same percentage can translate into a larger payment over time.
“However, for someone with a family history of illness, a senior citizen, or anyone likely to claim often, the savings on premium can be wiped out by a single hospitalisation,” says Joshi.
“This implies that it is necessary to understand what kind of claims the co-payment scheme applies to. It is good to know that such a decision will depend on your healthcare requirements and financial capability,” says Ramamurthy.
If co-pay becomes a standard feature rather than an option, people who would have picked a no co-pay plan may no longer have that choice.
That makes it more necessary for insurers and advisors to explain the payment in rupee terms. For policyholders, understanding that amount and keeping an emergency fund ready would be essential.
FAQs
1. Is a mandatory 10 per cent health insurance co-pay already in force?
The reported GIC proposal remains under discussion. It should not be treated as an implemented rule.
2. How much would I pay under a 10 per cent co-pay?
On an admissible claim of Rs 5 lakh, you would pay Rs 50,000. The insurer would pay Rs 4.5 lakh, subject to policy terms and limits.
3. Can my out-of-pocket expenses exceed the co-pay amount?
Yes. Non-payable items, room-rent differences, and other policy deductions may have to be paid separately, increasing your total expense.