

Summary of this article
Maharashtra Consumer Commission ordered Rs 70 lakh for burnt BMW
United India Insurance must pay seven per cent annual interest
Commission found no proven breach of motor insurance policy conditions
Insurers cannot unilaterally reduce agreed IDV during claim settlement
A Maharashtra consumer commission has directed United India Insurance Company to pay Ravikant S Patil Rs 70 lakh for his burnt BMW, along with seven per cent annual interest from the date the claim was rejected. It also awarded Rs 50,000 for mental agony and harassment and Rs 25,000 towards litigation costs. The order, passed on September 16, 2026, brings a 14-year dispute over the motor insurance claim to a decision. The amount ordered, including interest, is yet to be calculated and paid.
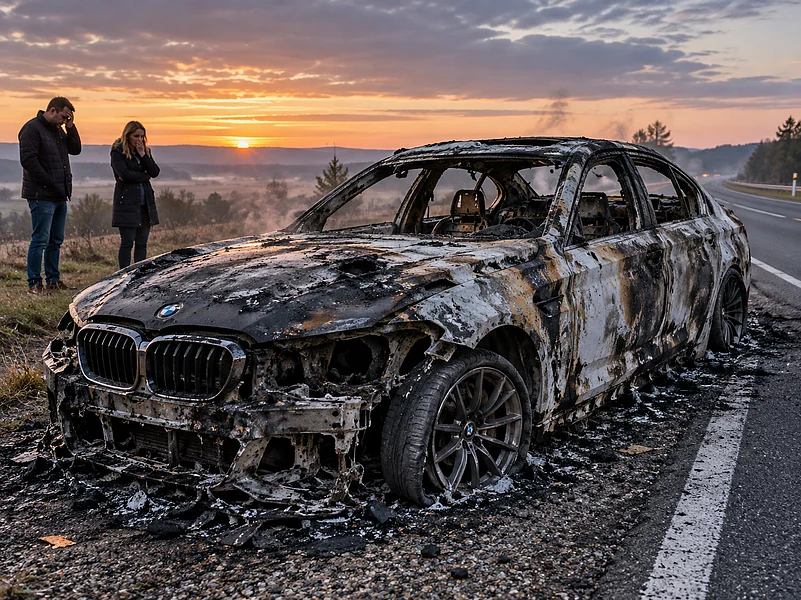
Patil’s BMW was insured for Rs 70 lakh under a policy valid from December 22, 2011 to December 21, 2012. On the night of March 8, 2012, the car suffered a tyre puncture near Dhulkhed in Maharashtra while he was travelling towards Solapur. With no mechanic or puncture repair facility available at that late hour, the driver moved the car to the roadside, locked it, and left with Patil in another vehicle. When they returned the next morning, the BMW had been completely burnt.
United India Insurance rejected the claim on November 23, 2012. It said Patil had breached Condition 4 of the policy by leaving the vehicle unattended without taking proper precautions to prevent further loss. The insurer also questioned why the driver did not use the spare tyre or arrange to tow the BMW. Patil approached the Maharashtra State Consumer Disputes Redressal Commission, alleging deficiency in service.
1 October 2026
Get the latest issue of Outlook Money

After earlier proceedings, the National Consumer Disputes Redressal Commission restored Patil’s complaint in 2018, giving him a final chance to present it on merits. The state commission issued its order after considering both sides.
What The Commission Considered
The dispute centred on whether leaving the car unattended automatically violated the policy. The commission found that Condition 4 did not impose an absolute ban on leaving a broken-down vehicle unattended. It required the insured to take proper precautions, which had to be assessed in the circumstances of the incident.
The car had been moved off the road, its windows were rolled up, and it was locked. The puncture occurred late at night, and the commission noted there was no repair facility or mechanic available nearby. It said personal safety could not be put at risk simply to guard a vehicle. The exact cause of the fire remained undetermined, and the insurer had not established a direct connection between Patil leaving the car and the loss, according to a recent report by NDTV.
What Policyholders Should Keep In Mind
The commission held that the steps taken were reasonable in the circumstances and that the insurer had not proved a breach of Condition 4. It also said the agreed insured declared value (IDV) of Rs 70 lakh should apply to the total loss. The insurer had argued that depreciation brought the car’s value down to Rs 59 lakh, but the commission said it could not unilaterally reduce the IDV at claim settlement.
The decision turns on policy wording and evidence; it does not mean every unattended vehicle will be covered. Policyholders should check their policy’s breakdown duties, take practical safety measures, and inform the insurer and police promptly. Photographs, location details, repair or towing records, official reports and written communication can help establish what happened and what precautions were possible.
If a claim is rejected, ask the insurer for its written decision, the policy clause relied on and the evidence behind the decision. A consumer commission can examine whether the insurer applied the clause fairly, but each case will depend on its facts and documents.
The supplied report and commission order contain no interview quotes, so I have not invented any.
FAQs
Does leaving a broken-down vehicle unattended automatically invalidate a motor insurance claim?
No. In this case, the commission assessed the precautions taken and the circumstances. The decision does not guarantee coverage in every similar case.
What did the commission order United India Insurance to pay?
It directed the insurer to pay the BMW’s Rs 70 lakh insured declared value, with 7 per cent annual interest from the claim rejection date, plus Rs 75,000 in compensation and costs.
What should policyholders do after a vehicle breakdown or claim rejection?
Take practical safety measures, inform the insurer and police promptly, and keep photos, reports, and repair or towing records. If a claim is rejected, ask for the reasons and the policy clause in writing.