

Summary of this article
Check health insurance coverage before arranging funds for hospital bills
Use emergency savings without compromising essential household expenses
Compare FD withdrawal penalties, investment losses, and loan costs
Maintain three to six months of expenses as emergency savings
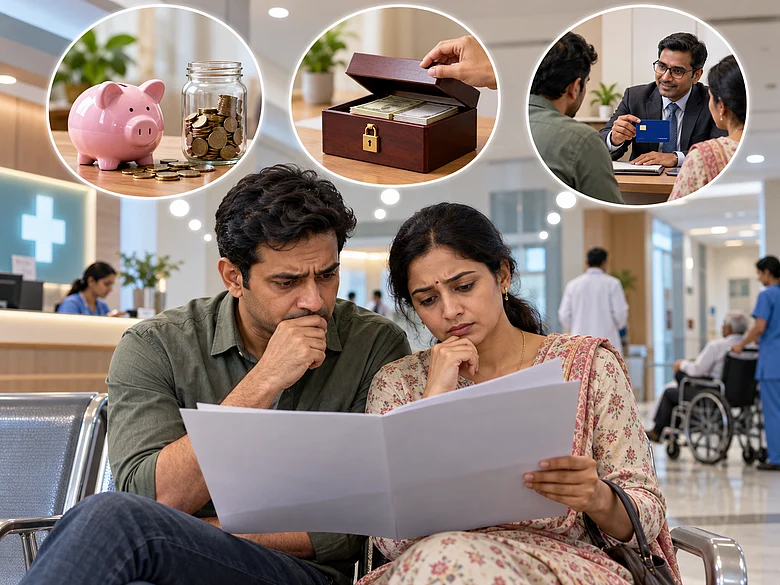
An unexpected hospital bill may be manageable on paper but difficult to pay without disrupting rent, school fees, or other monthly expenses. Families should first check what health insurance will cover, then weigh the cost of using savings, withdrawing from a fixed deposit (FD), selling investments, or borrowing.
The choice depends on more than the bill amount. It also depends on how much cash will remain, the penalties or taxes that may apply, and whether any loan repayment fits the household budget.
Use Savings, But Leave Room For Regular Expenses
An emergency fund is meant for costs that cannot wait. But paying the entire bill from savings may leave a family short for regular expenses due later in the month.
“I always suggest checking for available savings first. That’s the purpose of an emergency fund. But families also need to think about how much money they have left after paying the hospital,” says Jose Peter, co-founder & CEO, Arogya Finance, a healthcare financing company.
If the available savings are not enough to cover the bill while keeping household finances stable, the family could consider splitting the payment between savings and another source. The key is to avoid choosing a loan instalment that becomes difficult to manage alongside routine expenses.
“Paying part of the bill from savings and arranging the balance through financing may work better in some cases. What matters is whether the family can manage its regular expenses afterwards without struggling to repay,” says Peter.
Compare The Cost Of An FD, Investments, And A Loan
An FD can be an option if the cost of premature withdrawal is lower than the interest and charges on a loan. Check the interest lost and any penalty before closing it. Selling mutual funds or other investments also requires care: a market downturn could mean selling at a loss, while gains may have tax implications or the investment may carry an exit load.
“It boils down to three aspects primarily – the urgency factor, the cost implications, and the effect on the future course of action. Selling off investments amid a bearish market cycle means realizing losses, whereas borrowing leads to additional interest expenses, among others,” says Anooshka Soham Bathwal, CEO & founder, Dhanvesttor, a women-centric wealth management fund-house.
Bathwal says families should compare loan interest rates, processing charges and repayment periods, and check whether a hospital offers no-cost EMI. Borrowing may help preserve cash for essential expenses, but it can add avoidable costs if the family can pay without compromising its budget. Credit card borrowing can also become difficult to manage if the balance is not cleared in full.
“While breaking a FD to meet the requirement might sound like a feasible decision for such a small medical expense, the point here is that one must look into the early withdrawal penalty along with the foregone interest rate earned on the amount withdrawn,” says Bathwal.
Families should also check whether the bill is eligible for an insurance claim, while remembering that some expenses may need to be paid upfront or may not be covered. A loan should be considered only after comparing the total repayment with the cost of using available savings or an FD.
Peter recommends keeping enough readily accessible money to meet three to six months of essential household expenses. Families with elderly parents, ongoing medical needs or uncertain incomes may need a larger reserve. The money should be available quickly, rather than tied up in investments that might have to be sold at an unfavourable time.
Bathwal suggests considering a separate medical buffer, depending on the family’s needs. If savings are used, review the monthly budget and set aside a manageable amount regularly to rebuild the reserve.
“Having access to such a medical reserve will definitely prove helpful then. Now, assuming you do use this money someday, it is imperative to ensure that one starts thinking of rebuilding this reserve immediately,” says Bathwal.
FAQs
How should families pay an unexpected hospital bill?
Check insurance cover first, then use savings while keeping enough for regular expenses. Consider an FD, investments, or borrowing based on the costs involved.
When does it make sense to break an FD or take a loan?
Compare the FD’s premature withdrawal penalty and lost interest with the loan’s total interest, fees, and repayment schedule. Borrow only if repayments fit the household budget.
How much should families keep aside for medical expenses?
Keep three to six months of essential expenses readily accessible; families with ongoing medical needs or uncertain incomes may need a larger reserve.