





Until December 1983, when the Maruti 800 revolution hit India, buying a car was a luxury. The middle-class Indian was happy to hop on to scooters, which could be parked in the garages provided for two-wheelers with government housing. But with the introduction of Maruti 800, priced at almost half the cost of the Indian-made Ambassador and Premier Padmini, things started changing.
Liberalisation in the 1990s added wind to the sails; Indian and foreign car brands rolled in, while bank loans became more accessible. Not just cars, but homes and many expensive consumer durables were now within the reach of the middle-class. Loans brought in democratisation and empowered the middle class when it came to affording expensive or luxury goods. But borrowing has now taken a different form. It’s not just about big-ticket loans to afford luxury, but about everyday consumption to fulfil desires, such as posting a pretty picture on social media, giving in to the fear of missing out, and so on.
Data shows how popular a life on credit has become. Around 249 million people in India have taken some form of credit at some point or the other since 2017. That’s 28 per cent of the eligible population of 890 million, according to a 2026 TransUnion CIBIL report, Unlocking Access: Journey of Credit Expansion In India. The Reserve Bank of India’s (RBI) October 2026 report, Sectoral Deployment of Credit by NBFC, shows that the growth in retail loans went up to 22 per cent in August 2026 compared to 13.60 per cent a year ago. Besides, household debt reached 45.50 per cent of the gross domestic product (GDP) by end September 2025, shows RBI’s Financial Stability (FS) Report released in June 2026. Nearly half of these loans have been taken for consumption.
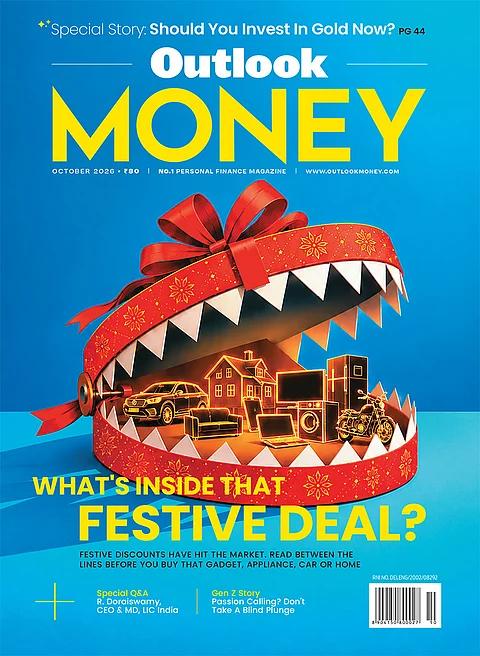
1 October 2026
Get the latest issue of Outlook Money

At the helm of this credit-for-consumption story are fintech firms that extend small-ticket loans. The FS Report shows fintech firms strengthened their position in the small-ticket personal loan segment (<`50,0000), with a market share of 56.80 per cent in March 2026 on the back of strong credit expansion of 41.60 per cent, well above the overall segment growth of 20.10 per cent. But rising credit is accompanied by rising delinquencies, pegged at 6.40 per cent, according to the RBI report. Unsecured loans form about 70.50 per cent of their total loan book, and about half of them were extended to borrowers under 35 years of age, the report adds.
It’s common to assume that small-ticket loans are manageable, but it is also a fact that they can pile up and easily spin out of control. For instance, the FS Report cites that borrower cash flows can get impacted if the overall economic conditions weaken due to the West Asia conflict.
With the festival and wedding season in full swing, loan offers are crowding the market along with discounts. Before you get swayed by how grand your festive celebrations or wedding should look, take stock of your repayment capacity. That depends on your cash flow, whether you have an emergency fund that can cover equated monthly instalments (EMIs) and your overall investment portfolio. Remember that debt can empower but it can also feed addiction to consumption and the lure of market profits.
Nidhi Sinha Editor, Outlook Money
nidhi@outlookindia.com





