





Summary of this article
Easy EMIs and festive offers can tempt people to spend more than they planned, only to feel the pinch when the bills start coming in after Diwali.
Before taking on another EMI, look at what you already pay each month and how much you need for household expenses and savings.
Paying just the minimum amount on a credit card may seem like a way out, but the unpaid balance can attract hefty interest. Setting a spending limit and sticking to it can help you enjoy the festivities without worrying about bills later.
The festive season has a way of making us spend a little more than we intended. A television that has been on the wish list for months suddenly looks affordable. A new phone seems worth buying when there is a discount, and a family holiday feels easier to plan when the payment can be split into monthly instalments. Credit cards, easy equated monthly instalments (EMIs) and buy-now-pay-later offers only add to the temptation.
The trouble is that the excitement of shopping rarely lasts as long as the repayments.
The real pinch often comes after Diwali. The shopping is done, the celebrations are over, and then the credit card bill arrives. EMIs begin to take a chunk out of the monthly salary, leaving less money for everyday expenses. Rent, groceries, school fees, insurance premiums and investments still have to be paid for, no matter how much was spent during the festive season.
Using credit for festive shopping is not necessarily a bad idea. The real question is whether you can repay what you spend without making the rest of your finances uncomfortable.

When Easy EMIs Make Spending Look Smaller
Consider a smartphone priced at Rs 60,000. Paying the entire amount at once may seem expensive, but an EMI of Rs 5,000 a month can make the same phone feel within reach. Now add a television, a washing machine and a few smaller purchases. Each instalment may look manageable on its own, but together they can take a sizeable bite out of the monthly salary.
The trouble is that shoppers often focus on whether they can afford the monthly instalment, without thinking about how much all these purchases will cost them in the end.
Zero-cost EMI is worth checking before you sign up. There may be processing fees, or you could miss out on a discount offered to customers paying upfront. Compare the final price under both options before deciding which one works out cheaper.
A high credit card limit can also give a false sense of how much you can afford. Just because a bank allows you to spend up to Rs 2 lakh does not mean you should. The amount you can borrow and the amount you can repay comfortably are two very different things.
How much debt you can handle depends on what your monthly salary has to cover. If you have few expenses and some money tucked away for emergencies, another EMI may be easy enough to manage. But if you are already paying a home loan, a car loan and your children's school fees, there may not be much left to spare.
Calculate how much of your income goes into other EMIs before taking up a new one. Whatever remains you will have to manage your house hold and expenses and savings.
Let’s say you earn Rs 1 lakh per month and your current EMI is 35,000, you need to think before taking another one on your shoulder. Before agreeing to another instalment, you need to work out how much is left after meeting regular household expenses and setting aside some money for savings.
If festive shopping adds another Rs 10,000 in monthly instalments, your total loan repayments rise to Rs 45,000. After paying Rs 45,000 in EMIs, you would have Rs 55,000 left from your Rs 1 lakh monthly income. That money would still need to cover groceries, bills, insurance, medical expenses and savings, along with anything unexpected that crops up during the month.
Whether that is enough depends on the household. A family with modest expenses may manage, but one paying high rent or supporting children and elderly parents could find itself short of money well before the next salary arrives.
As a general rule of thumb, keeping loan EMIs within 30–40 per cent of take-home pay can help prevent repayments from taking over the household budget. But the figure is only a starting point. Someone with high living expenses may struggle even at that level, while another person with fewer commitments may have more room to borrow.
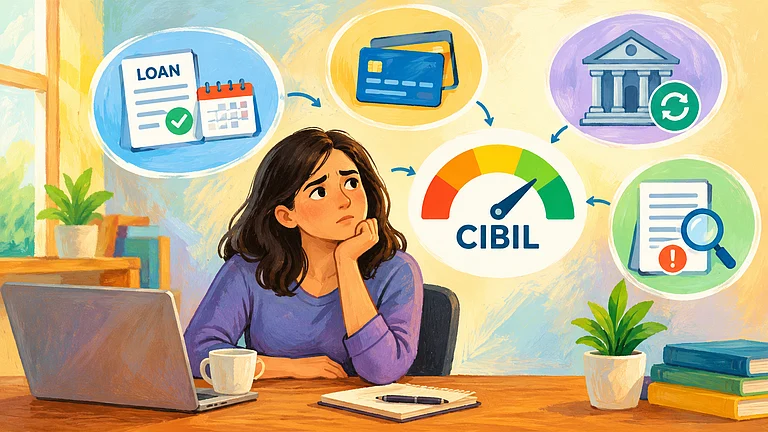
Credit card dues deserve even more attention. Paying only the minimum amount due can help avoid an immediate payment default, subject to the card's terms, but it does not mean the debt has been cleared. Interest can build up on the unpaid balance, and a purchase that initially seemed affordable can become much more expensive.
If you are already carrying a credit card balance from previous months, think twice before adding fresh festive purchases to it. Taking on more expensive debt to buy things you can postpone is rarely a good trade-off.
Don't Let A Sale Eat Into Your Savings
One of the easiest ways to lose control of festive spending is to shop first and work out the budget later. By then, the discounts may have proved too tempting to resist.
It is better to decide beforehand how much you can spend without borrowing beyond your means. Make a list of what you actually need, separate it from what you would simply like to buy, and put a limit on the total. If the money is not enough for everything, there is no harm in postponing a purchase.
Savings need protection, too. Money kept aside for medical emergencies, retirement, children's education or other important goals should not be used to fund an expensive shopping spree. A festive offer may last only a few days, but rebuilding savings can take months.
For bigger purchases, compare the cash price with the total amount payable through EMIs. Check the interest rate, processing charges, repayment period and conditions attached to any advertised discount. A lower monthly instalment may simply mean that you will be paying for the product for longer.
It is also worth asking whether you need the item immediately. If a new television or phone can wait another two or three months, saving towards it may be a better option than committing a part of every future salary to its repayment.
A Little Restraint Can Save Months Of Stress
Festivals are meant to be enjoyed. Buying gifts, updating household appliances or taking the family out should not automatically be seen as financial mistakes. The problem begins when spending is driven by the fear of missing a deal or the feeling that everyone else is buying something new.
A simple test can help before you swipe your card: after making this purchase, will I still be able to pay my regular bills, save something each month and handle an unexpected expense? If the answer is no, it may be time to reconsider.
Also, look beyond the EMI. A purchase that costs Rs 5,000 a month is not just a Rs 5,000 decision. It is a commitment that will continue to draw money from future pay cheques, even after the excitement of the festival has faded.
The best festive budget is not necessarily the one that allows you to buy everything on your list. It is the one that lets you celebrate without worrying about the next credit card bill.
A few purchases can make the festive season special. But there is little joy in spending the following months trying to pay for them.





