Summary of this article
Financial independence for a homemaker should not be measured only by whether she earns a salary. It is also about having financial awareness, access to money and assets in her own name.
A common mistake is to leave investing entirely to the earning spouse. A homemaker may know how much the family spends every month but may not know how much is invested, where the investments are held or what insurance policies the family has.
For a homemaker, investing may not begin with a large amount or a detailed financial plan. It could simply be the money left after the month's household expenses have been taken care of.
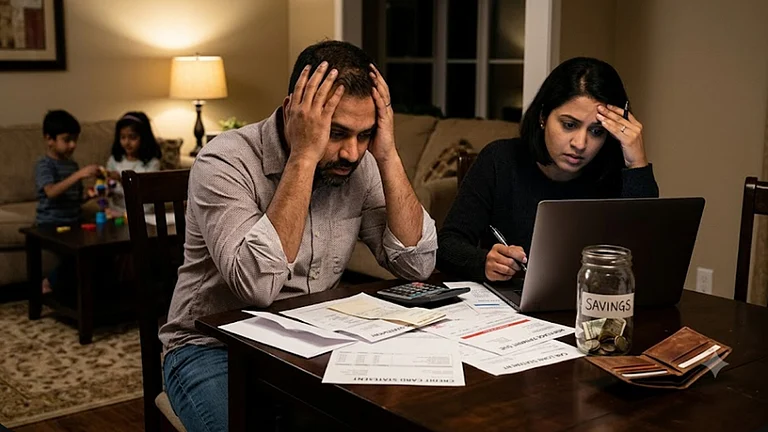
For many homemakers, the financial reality is a little complicated. They may be managing the household budget, paying bills, looking after children and making everyday spending decisions, yet have little money that they can call their own.
Not having a regular income, however, does not mean a homemaker cannot build financial security. The first step is to move from being only a household money manager to becoming an active participant in financial decisions.
Financial planners say financial independence for a homemaker should not be measured only by whether she earns a salary. It is also about having financial awareness, access to money and assets in her own name.
Start With Money You Can Access
A separate savings account can be a simple starting point. Even if the household income is earned by the spouse, setting aside a fixed amount every month for the homemaker can create a personal financial cushion.
The amount need not be large. A regular transfer of Rs 5,000 or even Rs 2,000 a month can eventually create a meaningful pool of money. The important part is that the money should be in an account in her own name and not be treated as part of the household's routine spending money.
This money can initially be used to build an emergency reserve. Ideally, a homemaker should have enough readily accessible funds to meet at least a few months of her personal expenses.
Don't Leave All Investments To The Spouse
A common mistake is to leave investing entirely to the earning spouse. A homemaker may know how much the family spends every month but may not know how much is invested, where the investments are held or what insurance policies the family has.
That needs to change.
She should maintain a basic record of bank accounts, fixed deposits, mutual funds, insurance policies, property documents, loans and other major financial assets. She should also know the family's monthly income, regular expenses and outstanding liabilities.
This is particularly important in an emergency. Financial knowledge can be as valuable as financial assets when a family suddenly has to manage without its primary income earner.
Start With What You Can Comfortably Set Aside
For a homemaker, investing may not begin with a large amount or a detailed financial plan. It could simply be the money left after the month's household expenses have been taken care of.
That is perfectly fine. The important thing is to make a beginning.
If Rs 2,000 or Rs 3,000 can be set aside every month without putting pressure on the household budget, that money can gradually be invested for a long-term goal. An SIP in a mutual fund could be one option for someone who is comfortable with market-linked investments and has a sufficiently long-time horizon. Money that may be needed sooner can be kept in more stable and easily accessible avenues.
The idea is not to turn every rupee into an investment. Homemakers often have to deal with unexpected expenses - a child's school requirement, a medical bill, a family function or simply a month when household expenses run higher than expected. Keeping some money readily available is, therefore, just as important as investing.
What matters is developing the habit of putting something aside for oneself, rather than waiting for there to be a “perfect” amount to invest.
Don't Forget About Ownership
Financial independence also means ownership. Homemakers should own investments and assets in their own names where possible. Don't assume that because there is family wealth you will automatically inherit it.
They should also understand the nomination details on bank accounts, investments and insurance policies and keep important documents accessible.
For homemakers, financial independence is rarely achieved through one dramatic financial decision. It is more often built quietly - by saving a little, investing regularly, understanding the family's money and making sure some assets are held in their own name.
The larger goal is not to separate household finances. It is to ensure that a woman who spends years managing the family's finances does not find herself financially unprepared when she needs money or has to make financial decisions on her own.