


Summary of this article
Home insurance may cover Diwali fire damage caused by neighbourhood crackers
Building and household contents require appropriate coverage under the policy
Underinsurance, exclusions, and policy violations may reduce or affect claim payouts
Fire brigade reports, photographs, and repair estimates help support insurance claims
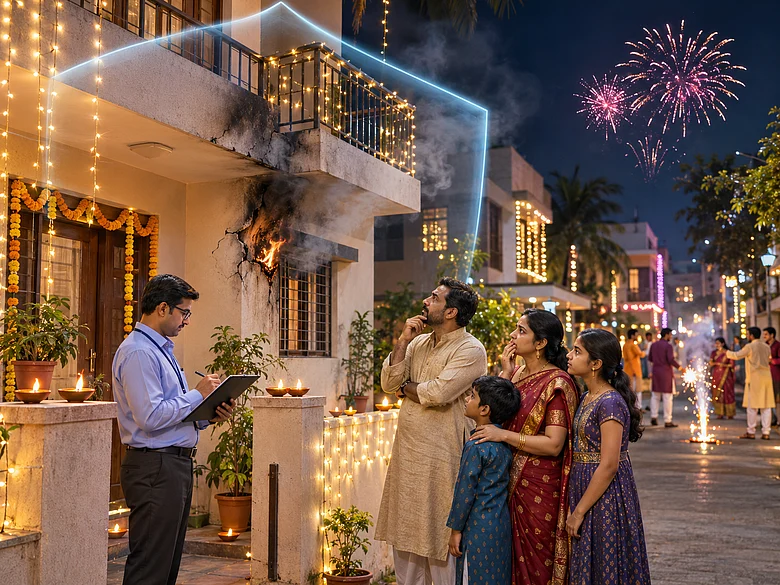
A stray rocket, spark, or firecracker can set curtains, furniture, or other parts of a home alight during Diwali. If the fire starts at a neighbour’s property and damages your house, you may be able to claim under your home insurance policy.
“In insurance terms, this is a classic accidental fire. You don’t need to get into an awkward blame game or legal battle with your neighbour before asking for help,” says Santosh Sahoo, vice president, Probus.
Whether a claim is paid, and how much, depends on the cover selected, the policy’s terms and the extent of the damage. Policyholders should check whether their policy covers the building, household contents or both, and note any exclusions and claim requirements.
Check What Your Policy Covers
A home insurance policy may cover the structure and household contents under separate sections, with separate insured amounts. Building cover is intended for the home itself, while contents cover applies to items such as furniture and appliances, subject to the policy terms. A policyholder should check that the relevant section is included; cover for the building does not automatically mean every item inside is insured.
“One protects the actual brick-and-mortar structure, while the other protects everything that would fall out if you turned the house upside down - your contents. If a fire breaks out, both are covered, provided the home is adequately valued,” says Sahoo.
The insured amount also matters. If the sum insured is lower than the actual cost of rebuilding or replacing what is covered, underinsurance can affect the settlement. For example, if rebuilding a house would cost Rs 50 lakh but it is insured for Rs 25 lakh, the cover may not be enough to meet the full loss. The payout for partial damage could also be reduced proportionately, depending on the policy’s terms.
“Imagine it actually costs Rs 50 lakh to completely rebuild your house, but the policy was only taken for Rs 25 lakh to keep things minimal. To prevent any shortfall in your payout, insurers always encourage policyholders to declare the true, accurate value of their property right at the start,” says Sahoo.
Homeowners should review the insured value when buying or renewing a policy and check how the insurer expects the building and contents to be valued. Keep purchase bills, photographs, or other records of valuable household items where available. These can help establish what was damaged and support the amount claimed.
Document The Damage And Follow The Claim Process
After a fire, make sure everyone is safe and contact the fire brigade. Once it is safe to do so, photograph or video the damage and prepare an itemised list of affected belongings. Keep bills, repair estimates and the fire brigade’s report, and notify the insurer promptly through the process set out in the policy.
“Call the fire brigade immediately because their official report is the golden ticket for your claim. But be careful about the fine print,” says Sahoo.
Avoid discarding damaged items before the insurer’s surveyor has inspected them, unless they pose a safety risk. Follow the insurer’s instructions and retain copies of the claim form and supporting documents. Missing paperwork or incorrect details can delay assessment or affect the settlement.
“Just keep in mind that things like missing paperwork, wrong details on your forms, or skipping the standard claim steps can slow things down or reduce your payout,” says Sahoo.
Exclusions and policy conditions can also matter. Sahoo cautions that storing commercial-grade crackers in a home could be treated as gross negligence and affect a claim. Intentional damage or false information can lead to rejection, while other breaches of policy conditions may reduce the payout. Read the wording for exclusions and claim steps, and provide accurate information when reporting the loss.
A neighbour’s role in causing the fire does not, by itself, mean the policyholder must first resolve a dispute before contacting the insurer. Report the damage, preserve the available evidence, and let the insurer assess the claim under the policy.
FAQs
Does home insurance cover fire damage caused by a neighbour’s firecracker?
It may be covered as accidental fire damage, subject to the policy’s terms, exclusions and claim requirements.
Will the policy cover both the house and its contents?
Only if the relevant building and contents covers are included. Check their insured amounts and whether they reflect the value of what is covered.
What should I do before filing a fire damage claim?
Prioritise safety, call the fire brigade, document the damage with photos or videos, list affected items, and notify the insurer promptly. Keep damaged items for inspection where safe.