







Summary of this article
Digital research influences 40 per cent of insurance sales today.
Most buyers prefer offline closing and seek human validation.
SLIP friction points cause digital buyers to drop out.
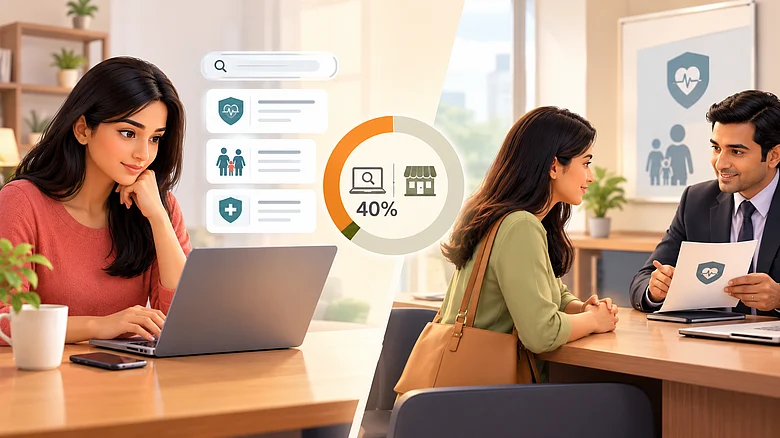
Digital influence is significantly influencing insurance buying behaviour of consumers in India. A newly published research report, titled Decoding the DICA Consumer: Redefining insurance distribution for India’s discerning buyers, by Google in collaboration with McKinsey & Company, reveals this shift in consumer behaviour. According to the report, buyers are using digital channels to educate themselves and compare different products, but making the final purchase predominantly offline.
Emerging DICA (Digitally Influenced, Closed With Assistance) Consumers
This shift is led by a distinct type of buyer, who explore online but make the final purchase offline. It terms this category as Digitally Influenced, Closed with Assistance (DICA) consumers. These consumers spend around 80 per cent of their research and purchase time on online platforms such as YouTube and mobile apps. It finds that approximately 78 per cent of consumers check two to three insurers online before ever speaking to a call centre representative or an advisor. Despite online search and engagement, less than 30 per cent feel comfortable buying their policy purely from digital routes.
Digital Influence Vs Direct Digital Sales
Compared to the digital influence on insurance buying decisions, the final purchase through offline channels shows a significant gap between overall digital influence and direct online conversion, the report highlights. Of the 50 million health and life insurance policies that are sold annually, only about 5 million (roughly 10 per cent) are closed directly through online channels.


The dominance of digital channels in influencing insurance purchases is reflected in the data. The report finds that digital touchpoints influence over 20 million annual purchases every year, which is more than 40 per cent of the industry’s total sales volume.
Pain Points Of DICA Consumers Leading To Non-Conversion
The report also highlights the reasons why influence is not ending in final conversion. It uses the term SLIP for it, to highlight four friction points where DICA buyers drop out during the exploration and final buy. Here, SLIP stands for S – Slow help (around 41 per cent feel that help arrives after their intent fades), L – Lost context (30 per cent have to restart conversations from scratch with new agents), I – Information mismatch (22 per cent experience discrepancies between online research and advisor details), and P – Personalisation gap (34 per cent want more tailored recommendations).
This indicates the scope: insurers and aggregators need to think about and work to improve the conversion rate.
Buyers Seek Human Validation
As per the report, buyers tend to avoid high-stakes financial transactions online, due to the inherent complexity of insurance products. An insurance product, whether life insurance or health insurance, demands long-term financial commitment spanning from 10 to 30 years; that’s why consumers don’t completely rely on the digital channel and instead seek human validation. Around 44 per cent of consumers seek involvement of a human to ensure that their money is safely invested. Around 33 per cent of the buyers value a human advisor for post-purchase support and accountability, and guidance if a medical issue arises. Another 28 per cent, the report reveals, rely on advisors to demystify complex insurance terms, exclusions, and other doubts arising from online research.
Higher Average Ticket Size And Expanding Geographic Reach
The report highlights the DICA segment as a growth opportunity for insurers. It also points out a higher average ticket size (40 per cent higher than the overall portfolio average) for the leads generated from digital influence. Simply put, DICA buyers have an 18-20 per cent likelihood of purchasing a rider to their base policies.
The report states that this behaviour is not restricted to metro cities. The top 20 non-metro cities are now increasingly having DICA consumers, almost double the national average of 10-12 per cent.
The report is based on the consumer survey of 1039 consumers and interviews with insurance advisors managing asset portfolios between Rs 15,000 and Rs 30,000 crore.by a distinct type of buyer, who explore online but make the final purchase offline. It terms this category as Digitally Influenced, Closed with Assistance (DICA) consumers. These consumers spend around 80 per cent of their research and purchase time on online platforms such as YouTube and mobile apps. It finds that approximately 78 per cent of consumers check two to three insurers online before ever speaking to a call centre representative or an advisor. Despite online search and engagement, less than 30 per cent feel comfortable buying their policy purely from digital routes.
Digital Influence Vs Direct Digital Sales
Compared to the digital influence on insurance buying decisions, the final purchase through offline channels shows a significant gap between overall digital influence and direct online conversion, the report highlights. Of the 50 million health and life insurance policies that are sold annually, only about 5 million (roughly 10 per cent) are closed directly through online channels.
The dominance of digital channels in influencing insurance purchases is reflected in the data. The report finds that digital touchpoints influence over 20 million annual purchases every year, which is more than 40 per cent of the industry’s total sales volume.

Pain Points Of DICA Consumers Leading To Non-Conversion
The report also highlights the reasons why influence is not ending in final conversion. It uses the term SLIP for it, to highlight four friction points where DICA buyers drop out during the exploration and final buy. Here, SLIP stands for S – Slow help (around 41 per cent feel that help arrives after their intent fades), L – Lost context (30 per cent have to restart conversations from scratch with new agents), I – Information mismatch (22 per cent experience discrepancies between online research and advisor details), and P – Personalisation gap (34 per cent want more tailored recommendations).
This indicates the scope: insurers and aggregators need to think about and work to improve the conversion rate.
Buyers Seek Human Validation
As per the report, buyers tend to avoid high-stakes financial transactions online, due to the inherent complexity of insurance products. An insurance product, whether life insurance or health insurance, demands long-term financial commitment spanning from 10 to 30 years; that’s why consumers don’t completely rely on the digital channel and instead seek human validation. Around 44 per cent of consumers seek involvement of a human to ensure that their money is safely invested. Around 33 per cent of the buyers value a human advisor for post-purchase support and accountability, and guidance if a medical issue arises. Another 28 per cent, the report reveals, rely on advisors to demystify complex insurance terms, exclusions, and other doubts arising from online research.
Higher Average Ticket Size And Expanding Geographic Reach
The report highlights the DICA segment as a growth opportunity for insurers. It also points out a higher average ticket size (40 per cent higher than the overall portfolio average) for the leads generated from digital influence. Simply put, DICA buyers have an 18-20 per cent likelihood of purchasing a rider to their base policies.
The report states that this behaviour is not restricted to metro cities. The top 20 non-metro cities are now increasingly having DICA consumers, almost double the national average of 10-12 per cent.
The report is based on the consumer survey of 1039 consumers and interviews with insurance advisors managing asset portfolios between Rs 15,000 and Rs 30,000 crore.





